Sami is 62, a retired machinist in Dearborn, Michigan, and he pays for nearly everything with one cash-back credit card: gas, groceries, and this week, two gallons of paint and a new garden hose at the hardware store. He has never paid a dollar of credit card interest, because he pays the full statement balance every month. Millions of Americans do the same. Millions of others carry a balance at an average rate above 22%. (Sami is a composite example, but both groups are very real.)
Those two groups explain most credit card statistics in the U.S. Americans owe more than $1.26 trillion on their cards, yet a growing share of accounts are paid in full every month. This roundup collects the latest credit card statistics from official sources, including the New York Fed, the Federal Reserve, the Philadelphia Fed, and the CFPB, with the date and source for every number.
Quick answer: Americans owed $1.26 trillion on credit cards in the second quarter of 2026, according to the New York Fed. The average interest rate on credit card accounts charged interest was 22.36% in August 2026. In 2025, 82% of U.S. adults had a credit card, and 45% of cardholders carried a balance at least once during the year. Card issuers charged consumers $160 billion in interest in 2024, plus $31.3 billion in fees.
Credit Card Statistics at a Glance
| Statistic | Latest figure | Source and date |
| Total U.S. credit card balances | $1.26 trillion | New York Fed, Q2 2026 |
| Average APR, accounts charged interest | 22.36% | Federal Reserve G.19, August 2026 |
| Adults with a credit card | 82% | Federal Reserve SHED, 2025 |
| Cardholders who carried a balance | 45% | Federal Reserve SHED, 2025 |
| Accounts paying the full balance | 36.9% | Philadelphia Fed, Q2 2026 |
| Accounts paying only the minimum | 10.15% | Philadelphia Fed, Q2 2026 |
| Delinquency rate on credit card loans | 2.85% | Federal Reserve, Q2 2026 |
| Interest charged to consumers | $160 billion | CFPB, 2024 |
| Fees paid by consumers | $31.3 billion | CFPB, 2024 |
| Purchase volume | $3.6 trillion | CFPB, 2024 |
How Much Credit Card Debt Do Americans Have?
Americans owed $1.263 trillion on credit cards at the end of the second quarter of 2026, according to the Federal Reserve Bank of New York’s Household Debt and Credit Report. That was up $21 billion from the first quarter and $54 billion from a year earlier.
Balances usually dip early in the year and climb again around the holidays. They peaked at $1.28 trillion at the end of 2025, according to the New York Fed’s fourth-quarter report, after rising $44 billion in the final quarter.
Credit cards are a small slice of total household debt, which stood at $18.8 trillion in the second quarter of 2026. Mortgages make up most of it. But card debt is the most expensive debt most families carry. For how cards compare with other kinds of borrowing, see our guide to types of loans.
The Federal Reserve’s broader measure of revolving credit, which is mostly credit card debt, was $1.35 trillion in August 2026, seasonally adjusted, according to its G.19 consumer credit release.
What Is the Average Credit Card Interest Rate in 2026?
The average interest rate on credit card accounts charged interest at commercial banks was 22.36% in August 2026, according to the Federal Reserve’s G.19 release. The average across all card accounts, including those that pay in full, was 21.19%.
Credit card rates jumped after the Federal Reserve raised interest rates in 2022 and 2023, and they have stayed high:
| Year | Average APR, accounts charged interest |
| 2021 | 16.45% |
| 2022 | 17.91% |
| 2023 | 22.15% |
| 2024 | 22.89% |
| 2025 | 22.32% |
| August 2026 | 22.36% |
Source: Federal Reserve, G.19 Consumer Credit (released Oct 7, 2026). August 2026 is preliminary.
Rates on many cards are higher still. The CFPB’s 2025 credit card market report found that average APRs in 2024 “reached 25.2 percent for general purpose cards and 31.3 percent for private label credit cards,” such as store cards.
How Many Americans Have a Credit Card?
In 2025, 82% of U.S. adults had a credit card, according to the Federal Reserve’s Survey of Household Economics and Decisionmaking (SHED), published in May 2026. That’s down slightly from a high of 84% in 2021.
Ownership rises sharply with income. Only 46% of adults with family income under $25,000 had a credit card, compared with 97% of those earning $100,000 or more.
There were 608 million open general purpose credit card accounts at the end of 2024, plus 185 million open private label (store) card accounts, according to the CFPB. That’s several cards for every cardholder.
How Many Americans Carry a Credit Card Balance?
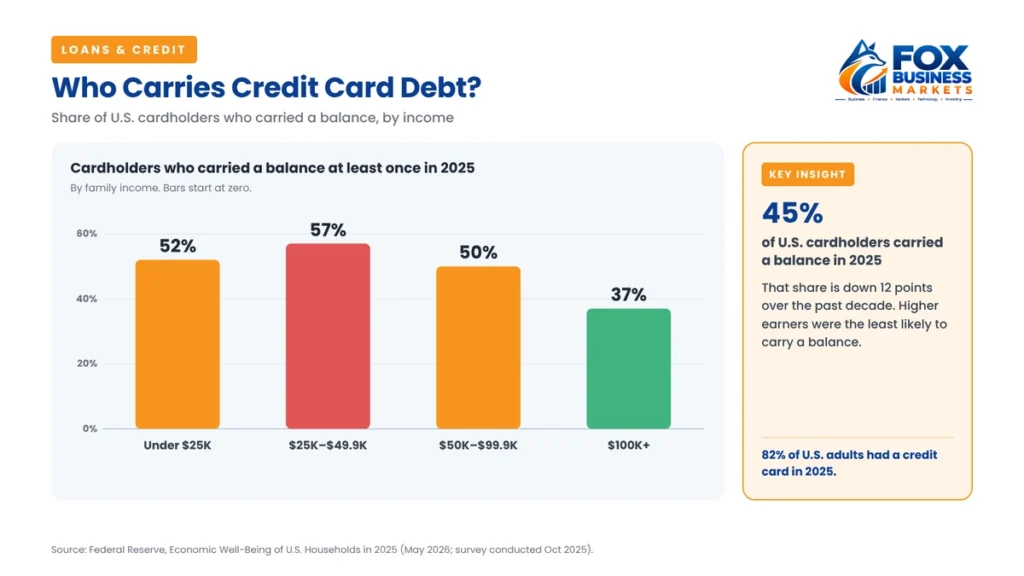
Among credit card statistics, this one may matter most for your wallet. In 2025, 45% of cardholders carried an unpaid balance at least once in the previous 12 months, according to the Fed’s SHED. That share is down 12 percentage points over the past decade.
Carrying a balance is more common among lower- and middle-income cardholders:
| Family income | Has a credit card | Carried a balance (cardholders) |
| Less than $25,000 | 46% | 52% |
| $25,000–$49,999 | 71% | 57% |
| $50,000–$99,999 | 88% | 50% |
| $100,000 or more | 97% | 37% |
Source: Federal Reserve, Economic Well-Being of U.S. Households in 2025 (May 2026).
The CFPB found a similar pattern from issuer data: the share of accounts that revolve a balance “returned to pre-pandemic levels of around 50 percent” in 2024.
How Do Americans Pay Their Credit Card Bills?
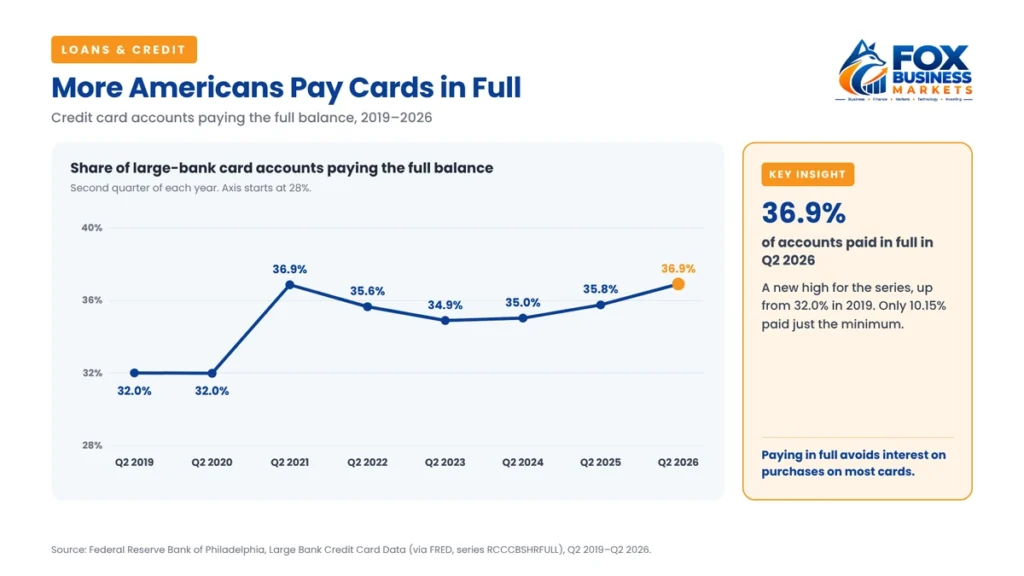
More cardholders are paying in full. In the second quarter of 2026, 36.9% of large-bank credit card accounts paid the full balance, according to the Federal Reserve Bank of Philadelphia’s large bank credit card data. That edges past the previous peak of 36.86% in the second quarter of 2021, when pandemic savings were high, making it the highest share in the series. It’s up from 32.0% in the second quarter of 2019.
At the other end, 10.15% of accounts made only the minimum payment in the second quarter of 2026, down from 10.72% a year earlier, according to Philadelphia Fed data published on FRED. Paying just the minimum on a card at 22% can stretch repayment out for years. Our guide on how to pay off debt explains faster methods.
The Philadelphia Fed also reported that total card balances at large banks grew 3.4% from a year earlier, while revolving balances, the ones that charge interest, grew only 1.5%.
How Much Do Credit Cards Cost Americans?
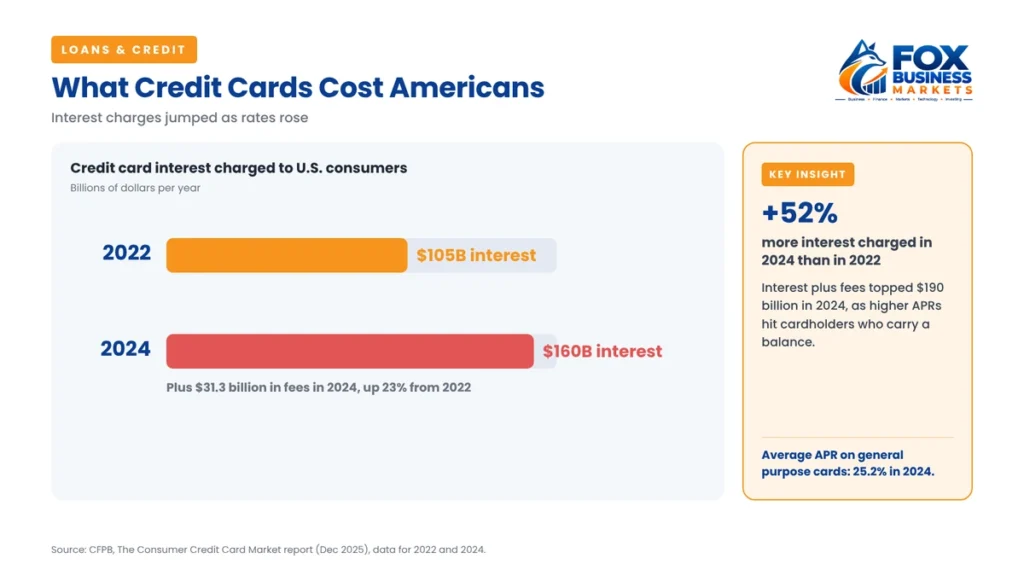
A lot. In 2024, consumers “were assessed $160 billion in interest charges, up from $105 billion in 2022,” the CFPB reported. They also paid $31.3 billion in fees, up 23% from 2022. Together, that’s more than $190 billion in a single year.
Americans also put $3.6 trillion of purchases on consumer credit cards in 2024, up from $3.2 trillion in 2022, according to the CFPB. Cards are the most common way to pay: the Federal Reserve’s 2025 payments study found that cards accounted for over three-quarters of noncash payments by number, and that credit card payments grew faster than debit card payments for the first time in almost a decade.
Are Credit Card Delinquencies Rising?
Not much, by most measures. The delinquency rate on credit card loans at commercial banks was 2.85% in the second quarter of 2026, seasonally adjusted, down from 3.04% a year earlier, according to Federal Reserve data on FRED.
The New York Fed’s measure is still elevated. About 6.97% of credit card balances moved into serious delinquency (90 days or more past due) at an annualized rate in the second quarter of 2026, up slightly from 6.93% a year earlier. The rate has hovered around 7% since 2024; it was 7.13% in the fourth quarter of 2025, versus 7.18% a year earlier.
Missing payments hurts more than your credit card account. Payment history is the biggest factor in your credit score; see how to improve your credit score if late payments have pulled yours down.
What Do These Credit Card Statistics Mean for You?
These credit card statistics point to a few practical lessons:
- Pay in full if you can. If you pay your full statement balance by the due date, most cards charge no interest on purchases. More than a third of accounts already do this.
- If you carry a balance, attack it. At 22% or more, a $5,000 balance costs roughly $1,100 a year in interest. A personal loan or a 0% balance transfer may cost less.
- Never pay just the minimum unless you have no other choice. It keeps you in debt longest.
- Watch your utilization. Keeping balances low relative to your limits helps your credit score.
- Build a cushion. An emergency fund keeps a surprise bill from landing on your card.
Frequently Asked Questions
How much credit card debt do Americans have in 2026?
Americans owed $1.26 trillion on credit cards in the second quarter of 2026, according to the Federal Reserve Bank of New York. That was up $21 billion from the first quarter and $54 billion from a year earlier. Balances hit a high of $1.28 trillion at the end of 2025.
What is the average credit card interest rate right now?
The average rate on credit card accounts charged interest at U.S. commercial banks was 22.36% in August 2026, according to the Federal Reserve. Across all accounts, including those paid in full, the average was 21.19%. Store cards often charge more; the CFPB found an average APR of 31.3% on private label cards in 2024.
What percentage of Americans have a credit card?
In 2025, 82% of U.S. adults had a credit card, according to the Federal Reserve’s Survey of Household Economics and Decisionmaking. Ownership ranges from 46% among adults earning less than $25,000 to 97% among those earning $100,000 or more.
What percentage of Americans pay their credit card in full?
In the second quarter of 2026, 36.9% of credit card accounts at large banks paid the full balance, according to the Philadelphia Fed. Among cardholders, 45% carried a balance at least once in 2025, according to the Federal Reserve, so a majority avoided interest all year.
How much do Americans pay in credit card interest?
Consumers were charged $160 billion in credit card interest in 2024, up from $105 billion in 2022, according to the CFPB. They also paid $31.3 billion in fees. Paying your full statement balance each month is the simplest way to avoid interest on purchases.
Are credit card delinquencies going up?
Not sharply. The delinquency rate on credit card loans at commercial banks fell to 2.85% in the second quarter of 2026, from 3.04% a year earlier, according to the Federal Reserve. The New York Fed’s rate of balances moving into serious delinquency was 6.97%, about the same as a year earlier.
The Bottom Line
Sami’s habit of paying in full is the best answer to the numbers in this report. Americans owe $1.26 trillion on credit cards, the average rate on balances that charge interest is above 22%, and consumers paid $160 billion in interest in 2024. But more than a third of accounts are paid in full, delinquencies have eased, and fewer cardholders carry a balance than a decade ago.
These credit card statistics show that a card can be a free, convenient payment tool or one of the most expensive loans you’ll ever take. The difference is whether you carry a balance. For the bigger picture, see our personal finance statistics and our personal finance guide.