Daniel was 54 and buying his first new truck in fifteen years when the finance manager slid the paperwork across the desk and said, “Good news, your score’s a 712.” Daniel, a high school shop teacher in Albuquerque, didn’t know whether that was good news. His bank’s app had shown him 748 the week before. Was 712 good? Why were the numbers different? And how much was that gap costing him? (Daniel is a composite example, but his confusion is one of the most common questions about credit.)
This guide answers what is a good credit score in the U.S., explains the FICO and VantageScore ranges, shows where the average American stands in 2026, and explains why the score your lender sees may not match the one in your app.
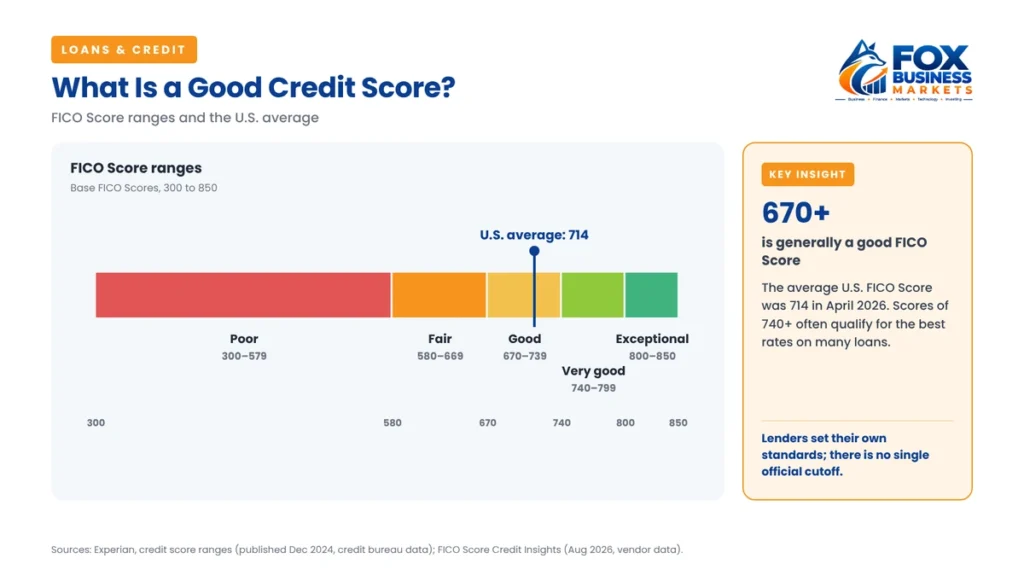
Quick answer: On the FICO scale of 300 to 850, a good credit score is 670 to 739, very good is 740 to 799, and exceptional is 800 or higher. The average U.S. FICO Score was 714 as of April 2026. Scores of 740 and above often qualify for the best rates on many loans, though some mortgage pricing tiers top out at 780, and what counts as “good enough” depends on the lender and the type of loan.
What Is a Good Credit Score?
So, what is a good credit score? Generally 670 or higher on the FICO scale, which most U.S. lenders use. Credit scores estimate how likely you are to repay borrowed money, based on the information in your credit reports from Equifax, Experian, and TransUnion.
There’s no single official cutoff, because each lender sets its own standards. But the common FICO ranges, as published by Experian (one of the three credit bureaus), are:
| FICO Score range | Rating | What it usually means |
| 800–850 | Exceptional | Best rates and terms from most lenders |
| 740–799 | Very good | Qualifies for most of the best offers |
| 670–739 | Good | Approved by most lenders at competitive rates |
| 580–669 | Fair | May qualify, often at higher rates |
| 300–579 | Poor | Harder to get approved; secured products may be needed |
Ranges for base FICO Scores, as published by Experian (credit bureau data).
What Is the Average Credit Score in the U.S.?
The average U.S. FICO Score was 714 as of April 2026, according to FICO’s Score Credit Insights report (vendor data), released August 25, 2026. That was flat from October 2025 and down one point from a year earlier.
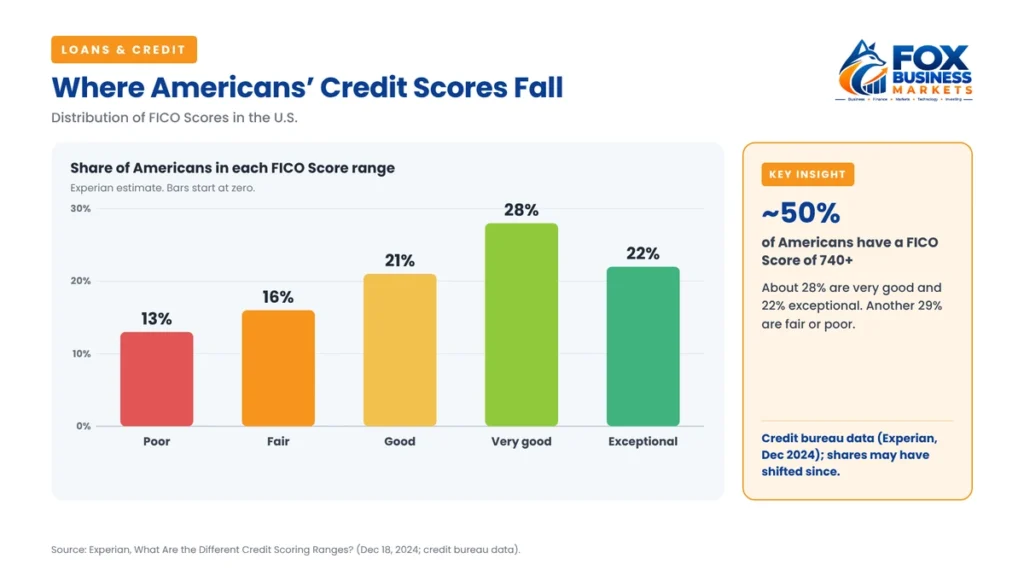
An average of 714 means the typical American is in the “good” range. Experian’s figures show about half of Americans (50%) have FICO Scores of 740 or higher: about 28% in the very good range and 22% in the exceptional range. About 21% are in the good range, 16% in fair, and 13% in poor, according to Experian’s breakdown (published December 2024, credit bureau data).
So when Daniel’s finance manager told him 712 was good news, he was right: it was almost exactly average. But it wasn’t “very good,” and that distinction can matter for the interest rate.
What Are the VantageScore Ranges?
VantageScore is the main competitor to FICO, created by the three credit bureaus. It also uses a 300 to 850 range, but it labels the bands differently. For VantageScore 3.0, Experian lists:
| VantageScore 3.0 range | Rating |
| 781–850 | Super prime |
| 661–780 | Prime |
| 601–660 | Near prime |
| 300–600 | Subprime |
Many free credit apps and card issuers show VantageScore, while many lenders, especially for mortgages and auto loans, use FICO. That’s a major reason your app score may not match the score a lender pulls.
Why Do You Have More Than One Credit Score?
Part of the confusion over what is a good credit score is that you have many credit scores, not just one. According to the Consumer Financial Protection Bureau (CFPB), your score “may differ depending on the scoring model,” the credit bureau that supplied the data, and even the day it was calculated.
That’s exactly what happened to Daniel. His bank’s app showed a VantageScore based on one bureau’s data. The dealership pulled a FICO Auto Score, an industry-specific version that ranges from 250 to 900 and is tuned to predict auto-loan repayment. Neither number was wrong; they were different scores built for different purposes.
The practical lesson: don’t panic if your scores don’t match. Watch the trend over time, and look at the factors behind your score. Our guide on how to improve your credit score explains what moves all of them.
What Credit Score Do You Need for a Mortgage, Car Loan, or Credit Card?
What is a good credit score for a specific loan? The credit score you need depends on the type of loan and the lender. Here’s what U.S. rules and lenders generally look for in 2026.
Mortgages. For FHA-insured mortgages, a score of 580 or higher can qualify for the maximum financing (a 3.5% down payment), while scores from 500 to 579 are limited to 90% loan-to-value, meaning a 10% down payment, according to the U.S. Department of Housing and Urban Development’s FHA handbook. Scores below 500 aren’t eligible. In Mortgagee Letter 2026-11, dated October 8, 2026, HUD said FHA will accept FICO 10T and VantageScore 4.0 alongside Classic FICO for case numbers assigned on or after January 1, 2027, while “the existing minimum credit score thresholds remain unchanged.”
For conventional mortgages, the Federal Housing Finance Agency said in July 2025 that lenders could deliver Fannie Mae and Freddie Mac loans using either Classic FICO or VantageScore 4.0. Separately, for loan files created on or after November 16, 2025, Fannie Mae removed the 620 minimum credit score for loans underwritten through its Desktop Underwriter system, which now relies on a broader risk analysis. Removing the minimum doesn’t guarantee approval, and higher scores still get better pricing.
Auto loans. There’s no legal minimum. Many lenders approve borrowers across the score range, but rates rise as scores fall. A score in the good range or higher usually helps you get competitive offers, especially from banks and credit unions.
Credit cards. Premium rewards cards usually look for good to excellent credit. If your score is fair or poor, a secured credit card can help you build credit.
Personal loans. Lenders set their own minimums, and rates vary widely by score. Our guide on how to get a personal loan explains how to compare offers.
How Much Does a Good Credit Score Save You?
A higher credit score generally means a lower interest rate, and on large loans the difference adds up. Because each lender prices loans differently, there’s no single number, but here’s the idea using a $30,000, five-year car loan:
| APR | Monthly payment | Total interest |
| 7% | About $594 | About $5,642 |
| 10% | About $637 | About $8,245 |
| 14% | About $698 | About $11,883 |
Illustrative calculation by Fox Business Markets; the APRs are examples, not rates tied to specific credit scores.
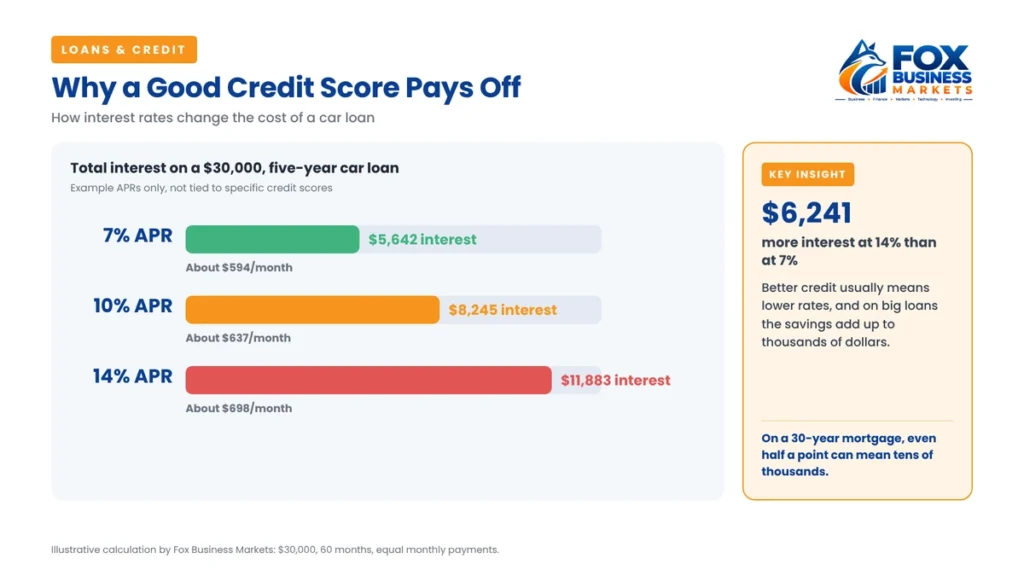
In this example, the gap between a 7% and a 14% loan is more than $6,000 in interest over five years. On a 30-year mortgage, even half a percentage point can mean tens of thousands of dollars.
What Doesn’t Affect Your Credit Score?
Knowing what is a good credit score also means knowing what doesn’t count. Your income, job, and savings balance aren’t part of your credit reports, so they don’t directly affect your score, although lenders look at them separately when you apply. According to myFICO, FICO Scores also don’t consider your race, color, religion, national origin, sex, marital status, or age, and the Equal Credit Opportunity Act generally bars lenders from discriminating on those bases (age protections have limited exceptions), as well as on receipt of public assistance.
Checking your own score doesn’t hurt it either. What does matter is how you’ve handled credit: whether you pay on time, how much of your available credit you use, how long you’ve had accounts, how often you apply for new credit, and the mix of accounts you have.
How Do You Move From Fair to Good Credit?
If your score is in the fair range (580 to 669), moving into the good range can be realistic for some people within months, not years. The biggest levers are the same ones that drive every FICO Score:
- Pay every bill on time. Payment history is about 35% of a FICO Score, so set up autopay for at least the minimum.
- Lower your credit card balances. Amounts owed are about 30% of the score; paying balances down can show up within a billing cycle or two.
- Check your reports for errors at AnnualCreditReport.com and dispute anything wrong.
- Avoid new applications you don’t need while you’re rebuilding.
- Keep older accounts open so your credit history keeps aging.
If your score is in the poor range, a secured credit card or a credit-builder loan from a credit union can help you start adding positive history. Our step-by-step guide on how to improve your credit score covers each of these in detail.
How Can You Check Your Credit Score?
You can usually check your credit score for free. Many credit card issuers, banks, and credit unions show a score in their apps, and some lenders provide the FICO Score they use. When you apply for a mortgage or auto loan, ask which score and range the lender used.
Your credit reports are free too. You can check your reports from all three bureaus every week at AnnualCreditReport.com. Checking your own score or report is a soft inquiry and doesn’t lower your score.
Frequently Asked Questions
What is a good credit score?
On the FICO scale of 300 to 850, a good credit score is 670 to 739, very good is 740 to 799, and exceptional is 800 or higher. Lenders set their own standards, but scores of 740 or more often qualify for the best rates on many types of credit in the U.S.
What is the average credit score in the U.S.?
The average U.S. FICO Score was 714 as of April 2026, according to FICO’s Score Credit Insights report released in August 2026. That falls in the “good” range. Experian’s figures show about half of Americans have FICO Scores of 740 or higher.
Is 700 a good credit score?
Yes. A 700 FICO Score is in the good range of 670 to 739 and close to the U.S. average of 714. Most lenders will approve you at competitive rates, though you may not get the very best offers, which usually go to borrowers with scores of 740 or higher.
Why is my credit score different on different apps?
You have many credit scores. Apps and lenders may use different scoring models, like FICO or VantageScore, different versions of those models, and data from different credit bureaus. The CFPB notes that scores can differ by model, data source, and even the day they’re calculated. Focus on the overall trend.
What credit score do I need to buy a house?
It depends on the loan. FHA loans allow scores as low as 580 with a 3.5% down payment, or 500 to 579 with 10% down. For conventional loans run through Fannie Mae’s Desktop Underwriter, there’s no longer a fixed 620 minimum, but higher scores still get better rates.
What is an excellent credit score?
An exceptional FICO Score is 800 to 850, and a very good score is 740 to 799. Above about 780, most borrowers already qualify for the best pricing, so pushing from 780 to 830 usually brings little extra benefit. On VantageScore 3.0, 781 to 850 is called super prime.
The Bottom Line
Daniel asked the dealership which score they’d pulled, then got a quote from his credit union, which used a FICO Score of 731. The credit union beat the dealer’s rate by about a percentage point (say, 8% instead of 9% on a $30,000, five-year loan), saving him more than $800 in interest.
That’s what a good credit score really means: not a single magic number, but a range that opens doors to better rates. On the FICO scale, 670 to 739 is good, 740 to 799 is very good, 800 and up is exceptional, and the U.S. average is 714. Know which score a lender is using, compare offers, and keep building your score with on-time payments and low balances. For more on borrowing, see our guide to the types of loans.