Two friends are starting a coffee roastery and stuck on the LLC vs corporation question. One wants an LLC because “it’s simpler.” The other wants a corporation because “that’s what investors want.” They’re both half right. The better question is which structure fits what they actually plan to do over the next five years.
The choice affects your taxes, your yearly paperwork, and whether investors will take you seriously. This guide explains the real differences using IRS rules and state law, with a worked tax example.
Quick answer: For most small businesses, an LLC is the better starting point. It’s simpler to run, profits are taxed once on your personal return, and it still protects your personal assets. A C corporation makes more sense if you plan to raise venture capital, offer stock options, or reinvest most of its profits to grow. An LLC can also elect S corporation tax treatment to cut self-employment taxes once profits are steady.
What Is an LLC? What Is a Corporation?
A limited liability company (LLC) is a business entity created under state law that shields its owners, called members, from personal liability for the business’s debts. The SBA describes it as a way to “take advantage of the benefits of both the corporation and partnership business structures” (SBA).
A corporation is a separate legal entity owned by shareholders and managed by a board of directors. According to the SBA, “Corporations can make a profit, be taxed, and can be held legally liable.” A C corporation is the standard version. An S corporation isn’t a different type of company; it’s a tax election that a corporation, or an LLC, can make with the IRS.
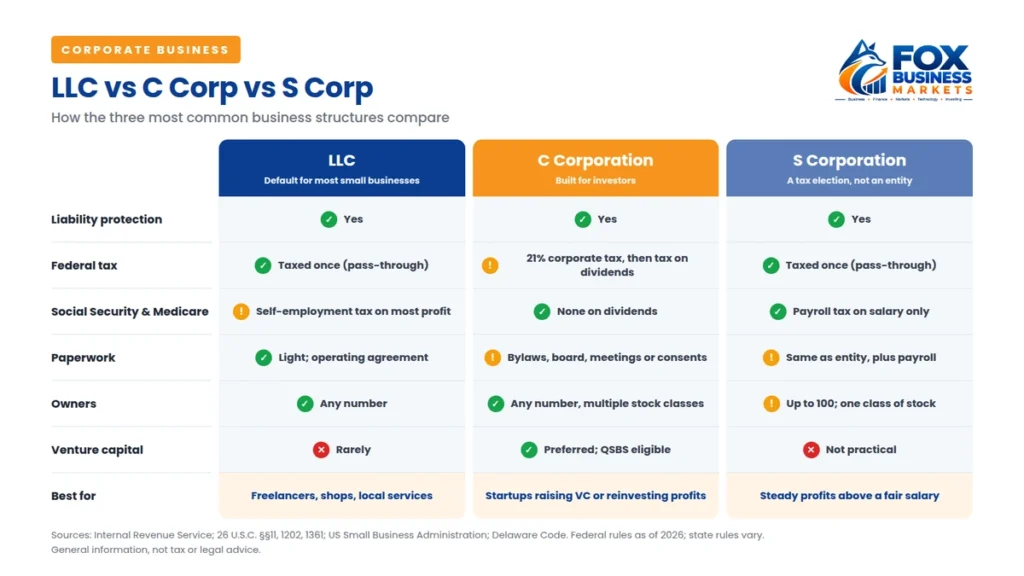
LLC vs Corporation at a Glance
LLC | C corporation | S corporation (tax election) | |
| Owners | Members, any number | Shareholders, any number | Up to 100 eligible shareholders |
| Personal liability protection | Yes | Yes | Yes |
| Default federal tax | Pass-through (taxed once) | Corporate tax, then tax on dividends | Pass-through |
| Social Security and Medicare | Self-employment tax on most active profits | None on dividends | Payroll taxes on salary only, not distributions |
| Management | Flexible; set by operating agreement | Board of directors and officers | Same as the underlying LLC or corporation |
| Ongoing formalities | Light | Bylaws, board, stockholder meetings or written consents, stock records | Same as the underlying LLC or corporation, plus payroll |
| Stock classes | Flexible ownership units | Multiple classes allowed | One class only (voting differences allowed) |
| Best for | Most small businesses | Venture-backed startups, companies planning to reinvest heavily | Profitable owner-operators paying themselves a salary |
How Are LLCs and Corporations Taxed?
This is where the LLC vs corporation choice matters most, and where much online advice is oversimplified.
LLCs are pass-through entities by default. Under IRS rules, “an LLC with only one member is treated as an entity disregarded as separate from its owner,” and an LLC with two or more members is taxed as a partnership, unless it elects otherwise on Form 8832 (IRS). Profits flow onto the owners’ personal returns, and active owners pay self-employment tax of 15.3% on most of those profits, covering Social Security and Medicare (IRS). Owners can also take the qualified business income (QBI) deduction of up to 20%, which the 2025 tax law made permanent. It’s capped at 20% of taxable income, and some higher-earning service businesses face limits (26 U.S.C. §199A).
C corporations face two layers of tax. The corporation pays a flat 21% federal tax on profits (26 U.S.C. §11). In the IRS’s words, profit “is taxed to the corporation when earned, and then is taxed to the shareholders when distributed as dividends. This creates a double tax” (IRS). Qualified dividends are taxed at 0%, 15%, or 20%, depending on income, plus a 3.8% net investment income tax for higher earners. A corporation that piles up cash with no business reason can also face a 20% accumulated earnings tax (26 U.S.C. §531).
A Worked Example: $100,000 in Profit
Here’s how federal taxes compare for a single owner with $100,000 in business profit, no other income, and the 2026 standard deduction of $16,100 (IRS, Rev. Proc. 2025-32):
LLC (pass-through) | C corp (all profit paid as dividends) | |
| Self-employment tax | $14,130 | $0 |
| Corporate tax (21%) | $0 | $21,000 |
| Personal income tax | $8,235 (after the QBI deduction) | $2,018 (on $79,000 of dividends) |
| Total federal tax | $22,365 | $23,018 |
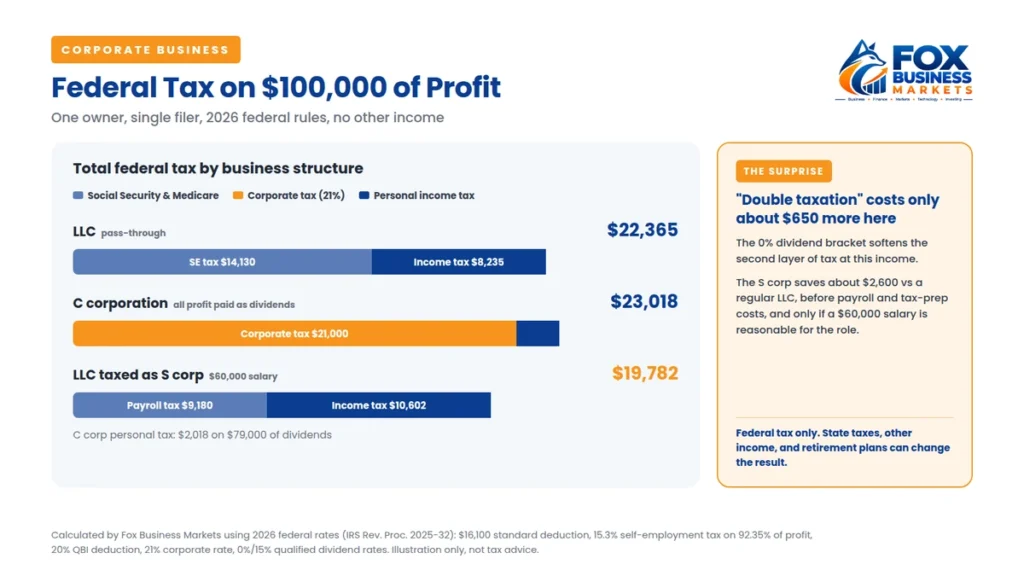
The result surprises many people: in this LLC vs corporation comparison, the totals are within about $650. Double taxation is softened because a single filer’s first $49,450 of taxable income is in the 0% bracket for qualified dividends in 2026. But the C corp owner earns no Social Security credits on dividends, and the math shifts quickly with higher income, other household income, or state taxes. This example covers federal tax only, so treat it as an illustration, not a plan.
The S Corporation Option
An LLC or corporation can elect S corporation status by filing Form 2553 with the IRS. The election must be filed no more than 2 months and 15 days after the start of the tax year it should take effect, or at any time during the year before; relief for late elections is sometimes available (IRS). To qualify, the business must have no more than 100 shareholders, only one class of stock, and only eligible shareholders, such as individuals, estates, and certain trusts, not partnerships, corporations, or nonresident aliens (IRS).
The appeal: an S corp owner who works in the business takes a salary, which is subject to payroll taxes, and can take the remaining profit as distributions, which aren’t. Using the same $100,000 example, a $60,000 salary would carry about $9,180 in Social Security and Medicare taxes, compared with about $14,130 in self-employment tax as a regular LLC. But wages don’t count toward the QBI deduction, so the owner’s income tax goes up. Net federal savings come to roughly $2,600 a year, before extra costs like payroll processing, unemployment taxes, and a separate tax return.
The catch is the salary. The IRS says S corporations “must pay reasonable compensation to a shareholder-employee” before taking distributions, based on factors like duties, experience, and “what comparable businesses pay for similar services” (IRS). Low salaries are a known IRS enforcement focus, and the IRS can treat distributions as wages.
Is One Safer Than the Other for Liability?
Both protect your personal assets from business debts and lawsuits in most cases. The SBA notes that “LLCs protect you from personal liability in most instances,” while “Corporations offer the strongest protection to its owners from personal liability.”
Neither is bulletproof. Courts can “pierce the corporate veil” and hold owners personally liable, most often when owners mix personal and business money, start the company badly undercapitalized, or use it to commit fraud (Cornell Law School). Courts can pierce an LLC’s veil too, and the rules vary by state. The practical protection is the same for both: keep a separate bank account, sign contracts in the company’s name, and carry business insurance.
What Paperwork Does Each Require?
Corporations come with more formal rules. Under Delaware law, a corporation’s affairs “shall be managed by or under the direction of a board of directors” (Delaware Code §141). Corporations also adopt bylaws, keep a stock ledger, and elect directors at an annual stockholder meeting, though stockholders and directors can often act by written consent instead (Delaware Code).
An LLC is governed mainly by its operating agreement, which Delaware law defines broadly as any agreement of the members “as to the affairs of a limited liability company and the conduct of its business” (Delaware Code). No board meetings or shareholder votes are required unless the agreement calls for them.
State fees differ too. Here are a few examples from official state sources:
State | LLC formation | LLC yearly cost | Corporation formation | Corporation yearly cost |
| Delaware | $110 | $400 annual tax (from 2026) | From $109 | Franchise tax from $175, plus $50 annual report |
| California | $70 | $800 minimum tax, plus an extra fee ($900 to $11,790) once total California income reaches $250,000 | $100 | $800 minimum franchise tax (not due in the first taxable year), or 8.84% of net income if higher |
| Texas | $300 | No franchise tax due under $2.65 million in revenue (2026) | $300 | Same threshold |
| Florida | $125 (including registered agent) | $138.75 annual report | $70 (including registered agent) | $150 annual report |
Sources: Delaware, California FTB and Secretary of State, Texas Comptroller, Florida Sunbiz. Fees change, so confirm with your state before filing. One Delaware trap: startups with millions of authorized shares can get a franchise tax bill in the tens of thousands of dollars under the default method. Recalculating with the assumed par value capital method, which has a $400 minimum, usually brings it down sharply.
Why Do Investors Prefer C Corporations?
If you plan to raise venture capital, investors usually expect a C corporation, most often in Delaware, for three reasons:
- Stock and options. Corporations can issue preferred stock to investors and incentive stock options to employees. Under the tax code, incentive stock options can only be granted by a corporation, including an LLC that has elected to be taxed as one (26 U.S.C. §422).
- Tax-free gains on startup stock. Qualified small business stock (QSBS) lets investors and founders exclude gains from federal tax. The 2025 tax law expanded it for stock issued after July 4, 2025: a 50% exclusion after three years, 75% after four, and 100% after five, with the cap raised to the greater of $15 million or 10 times your basis per company. Only C corporation stock qualifies, and some fields, such as health, law, and consulting, are excluded (26 U.S.C. §1202).
- Delaware reports that over two-thirds of Fortune 500 companies are incorporated there, along with nearly 70% of US-based IPOs in 2025 (Delaware Division of Corporations). Some large companies have recently moved to Texas or Nevada, but Delaware remains the default for startups.
Can You Switch From an LLC to a Corporation Later?
Yes. Many states, including Delaware, let an LLC convert directly into a corporation by filing a certificate of conversion, and the company is treated as the same entity (Delaware Code §265). For tax purposes, the conversion is generally treated as a transfer of the LLC’s assets to the corporation in exchange for stock (IRS, Rev. Rul. 2004-59). The QSBS clock starts at conversion, and only growth after that date can qualify, so founders planning to raise money often convert early.
One recent change worth knowing: in 2026, FinCEN permanently removed beneficial ownership (BOI) reporting for US companies, so most domestic LLCs and corporations no longer file those reports (FinCEN).
LLC vs Corporation: Which Should You Choose?
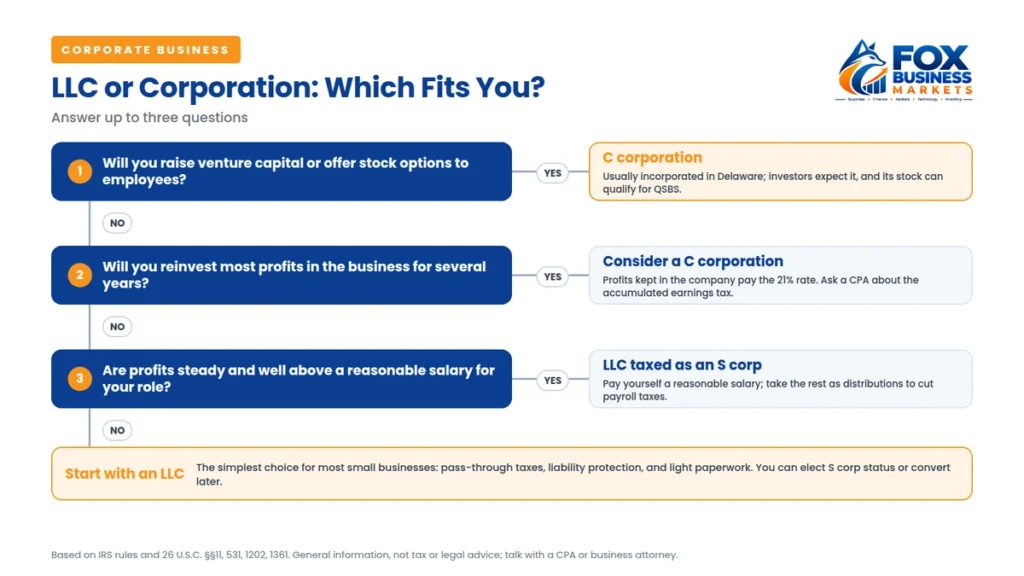
Here’s a direct way to settle the LLC vs corporation choice:
- Choose an LLC if you’re a freelancer, consultant, local service business, or shop; you don’t plan to raise outside equity; and you want the least paperwork.
- Consider an LLC taxed as an S corp if your profit is steady and comfortably above what a reasonable salary for your role would be.
- Choose a C corporation if you plan to raise venture capital, want to grant stock options, or expect to reinvest most profits for growth.
For more on setting up, see our guides on how to start a small business and how to write a business plan.
Common Mistakes
The biggest LLC vs corporation mistake is choosing a corporation “for investors” when no investors are coming, and then paying for years of extra paperwork. Others include electing S corp status too early, paying yourself an unreasonably low S corp salary, forming in Delaware when you only operate in one other state (you’ll usually pay fees in both), and mixing personal and business money, which weakens your liability protection.
This article is for general information, not tax or legal advice. Talk with a CPA or business attorney about your situation.
Frequently Asked Questions
What is the main difference between an LLC and a corporation?
An LLC is a flexible entity with pass-through taxation by default and few required formalities. A corporation is owned by shareholders, managed by a board of directors, and, as a C corporation, pays corporate tax on profits before shareholders pay tax on dividends.
Is an LLC or corporation better for taxes?
It depends on your income and plans. An LLC avoids double taxation, but owners pay self-employment tax. A C corporation pays a flat 21% federal tax and can retain earnings. At $100,000 of profit for a single owner, total federal tax can be similar under both.
Can an LLC be taxed as an S corporation?
Yes. An LLC can file Form 2553 to be taxed as an S corporation if it meets the requirements, such as having no more than 100 eligible owners and one class of ownership. Owners who work in the business must then pay themselves a reasonable salary.
Do investors invest in LLCs?
Venture capital investors usually prefer C corporations, especially Delaware corporations, because they can issue preferred stock and stock options, and because only C corporation stock qualifies for the QSBS tax exclusion. Some angel investors and lenders do work with LLCs.
Is a corporation safer than an LLC for liability?
Both protect owners’ personal assets in most cases. Either can lose that protection if owners mix personal and business funds, undercapitalize the company, or commit fraud. Keeping finances separate matters more than the entity type.
Can I change from an LLC to a corporation later?
Yes. Many states allow a statutory conversion, and the IRS generally treats it as a transfer of the LLC’s assets to a new corporation for stock. Founders who plan to raise venture capital often convert early to start the QSBS holding period.
The Bottom Line
The LLC vs corporation debate usually comes down to one question: are you building a business to run, or a company to sell shares in? The coffee roasters settled it by being honest about their plans. They formed an LLC to open the first shop, agreed to revisit S corp status once profits were steady, and planned to convert to a C corporation only if they ever raised outside money for a second location.