Learning how to write a business plan comes down to answering a few clear questions on paper: what your business does, who your customers are, how you’ll reach them, who runs the company, how much money you need, and how you’ll make a profit. A good plan turns an idea into a roadmap you can follow, and it gives lenders and investors a reason to back you.
You don’t need to write a 50-page document. The US Small Business Administration (SBA) says a lean plan can be “typically only one page.” This guide explains how to write a business plan step by step, using the SBA’s current structure, with a sample executive summary and a one-page plan example.
Key Takeaways
- There are two main formats: a detailed traditional plan and a one-page lean plan.
- A traditional plan has eight core sections, from the executive summary to financial projections.
- The SBA recommends financial projections for the next five years, with monthly or quarterly detail for year one.
- In one study of 1,088 founders, entrepreneurs who wrote formal plans were 16% more likely to build a viable business.
- Free templates and mentoring are available from SCORE, which has more than 10,000 volunteer mentors.
How We Researched This
To explain how to write a business plan accurately, we used the SBA’s current business plan guidance, updated in September 2026, along with SCORE, peer-reviewed research on business planning, and Bureau of Labor Statistics (BLS) data. Many websites still list nine SBA sections, including an appendix. The SBA’s current page lists eight, and this guide follows that version.
What Is a Business Plan, and Do You Need One?
A business plan is a written document that describes your business, your market, and your plan for making money. Before you learn how to write a business plan, it helps to know why it matters. It helps you think through your idea, spot problems early, and explain your business to others.
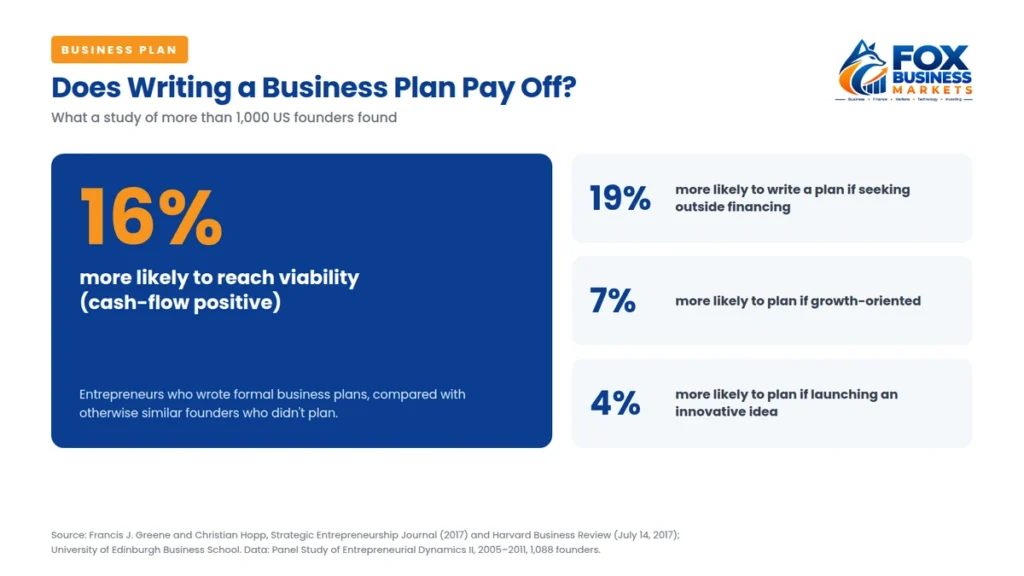
You’ll almost certainly need one if you plan to borrow. The SBA says “most lenders expect a business plan when you apply for startup funding” (SBA). Even if you’re self-funding, research shows planning helps. Francis Greene and Christian Hopp studied 1,088 US founders and found that “entrepreneurs who write formal plans are 16% more likely to achieve viability” than similar entrepreneurs who don’t plan (Harvard Business Review). A broader review of earlier studies reached a similar conclusion: “planning is beneficial,” though the effect depends on factors such as how new the business is (Brinckmann, Grichnik, and Kapsa, 2010).
A plan also helps you prepare for a tough reality: only 51.4% of new business locations are still open after five years, according to the BLS (BLS).
Traditional vs. Lean Business Plan
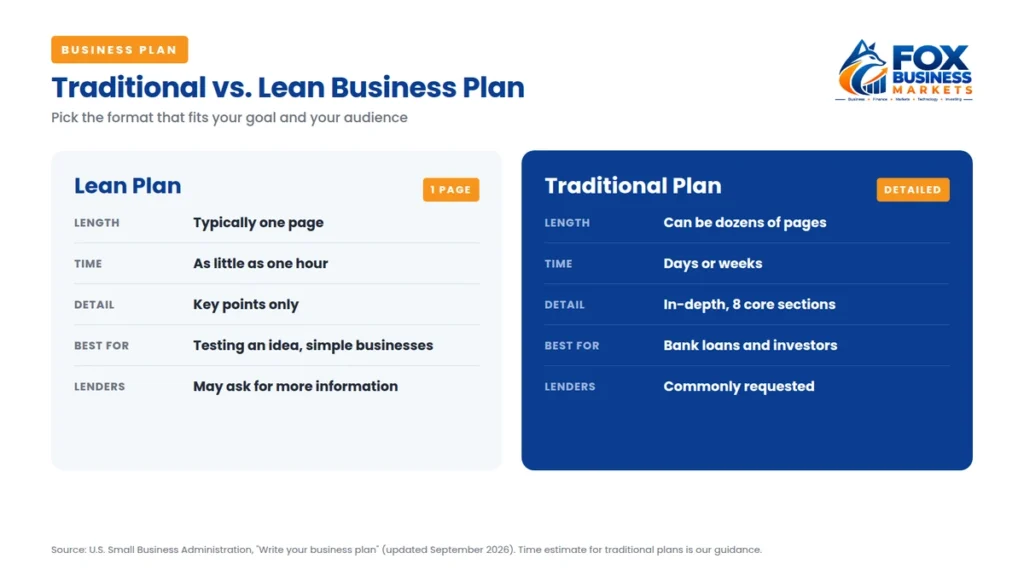
The SBA describes two formats (SBA):
Traditional business plan | Lean business plan | |
| Length | “Can be dozens of pages long” | “Typically only one page” |
| Time to write | Days or weeks | “As little as one hour” |
| Detail | In-depth for every section | Key points only |
| Best for | Bank loans, investors, complex businesses | Testing an idea, simple businesses, internal planning |
| Lender view | “Lenders and investors commonly request this plan” | “Some lenders and investors may ask for more information” |
If you’re unsure, start with a lean plan. You can expand it into a traditional plan when you apply for funding.
How to Write a Business Plan in 9 Steps
Here’s how to write a business plan using the SBA’s traditional structure. The SBA notes that you can “use the sections that make the most sense for your business and your needs.”
Step 1: Choose Your Format and Audience
Decide who will read your plan. A bank wants proof you can repay a loan. An investor wants to see growth potential. If the plan is just for you, a lean plan may be enough. Your audience decides how much detail you need.
Step 2: Write the Executive Summary
The executive summary is a one-page overview of your whole plan. The SBA’s advice: “Briefly tell your reader what your company is and why it will be successful.” Include your mission, your product or service, your target customers, and, if you’re seeking money, how much you need. Many owners write this section last, once the rest of the plan is done.
Sample executive summary (illustrative example):
Green Leaf Lawn Care is a residential lawn service launching in Columbus, Ohio, in spring 2027. We will offer weekly mowing, edging, and seasonal cleanups to homeowners in three suburbs where demand outpaces local providers. Our owner has eight years of landscaping experience. We are seeking a $40,000 equipment loan and project break-even within 10 months, based on 60 recurring customers.
Step 3: Describe Your Company
Explain what your business does, the problem it solves, and who it serves. Include your legal structure, location, and what makes you different from competitors. This is where your business strategy comes through: why customers will choose you.
Step 4: Analyze Your Market
Show that you understand your industry and customers. Describe your target market, its size, trends, and your main competitors, including their strengths, weaknesses, and prices. Use real data where you can, and cite your sources. Our roundup of small business statistics can help with industry context.
Step 5: Explain Your Organization and Management
Describe who runs the business and their experience. Include your legal structure, an organizational chart if you have employees, and any key advisors. Lenders and investors often bet on people as much as ideas, so highlight relevant experience.
Step 6: Describe Your Products or Services
Explain what you sell, how it benefits customers, and how you price it. Mention the product life cycle, any intellectual property such as trademarks or patents, and plans for new products.
Step 7: Outline Your Marketing and Sales Plan
Explain how you’ll attract and keep customers. Cover your pricing, sales channels, advertising, and the steps a customer takes before buying. Be specific: “social media” is vague, while “two posts a week on Instagram plus a referral discount” is a plan.
Step 8: Make Your Funding Request
If you’re seeking money, the SBA says to “clearly explain how much funding you’ll need over the next five years” and what you’ll use it for. State whether you want a loan or equity investment, the terms you’d like, and how you’ll repay it. Our guide to small business loans explains the main options.
Step 9: Build Your Financial Projections
This section shows whether your business can make money. The SBA advises providing “a prospective financial outlook for the next five years,” including “forecasted income statements, balance sheets, cash flow statements, and capital expenditure budgets.” For the first year, it says to “be even more specific and use quarterly — or even monthly — projections.”
If your business already operates, the SBA suggests including income statements, balance sheets, and cash flow statements “for the last three to five years.” Make sure your projections match your funding request. Our startup cost calculator and business revenue calculator can help you build the numbers.
One-Page Lean Business Plan Example
A lean plan covers nine elements, according to the SBA. Here’s how they might look for the same lawn care business (illustrative example):
Element | Example |
| Value proposition | Reliable weekly lawn care with online booking and no contracts |
| Customer segments | Homeowners in three suburbs, ages 35 to 70 |
| Channels | Door hangers, neighborhood social media groups, referrals |
| Customer relationships | Same crew every week, text reminders, seasonal check-ins |
| Key activities | Mowing, edging, cleanups, scheduling |
| Key resources | Truck, trailer, commercial mowers, a two-person crew |
| Key partnerships | Equipment dealer, local garden center |
| Cost structure | Equipment loan payments, fuel, insurance, labor |
| Revenue streams | Weekly service fees, seasonal cleanup packages |
What Lenders Look For in a Business Plan
The SBA says lenders want to see that you understand “your business’ finances, how the funds will be used, and how you’ll pay back the loan” (SBA). They also look at your credit and whether you can offer collateral. To make your plan lender-ready:
- Keep projections realistic and explain your assumptions.
- Show how loan payments fit into your monthly cash flow.
- Highlight relevant experience.
- Back up market claims with data.
- Make sure every number matches across sections.
Common Business Plan Mistakes
Knowing how to write a business plan also means avoiding these errors:
- Overly optimistic projections. Base revenue forecasts on real prices and realistic customer numbers.
- Ignoring competitors. Saying you have “no competition” is a red flag to lenders.
- Too much jargon. Write so anyone can understand your business.
- No clear funding ask. State exactly how much you need and why.
- Treating it as a one-time task. Update your plan at least once a year, or when something major changes.
Free Tools and Help
You don’t have to figure out how to write a business plan alone:
- SCORE offers free business plan templates, including versions for startups and established businesses, plus financial projection and cash flow templates (SCORE). Its “more than 10,000 volunteer mentors” provide free help, and “mentoring is always free, for the life of your business” (SCORE).
- Small Business Development Centers offer free one-on-one consulting at local centers.
- The SBA’s online guide walks through each section of a traditional and lean plan.
If you’re still at the idea stage, start with our guide on how to start a small business.
Frequently Asked Questions
How long should a business plan be?
It depends on the format. The SBA says a lean plan is typically one page, while a traditional plan “can be dozens of pages long.” Write as much as your audience needs, and no more.
What are the main parts of a business plan?
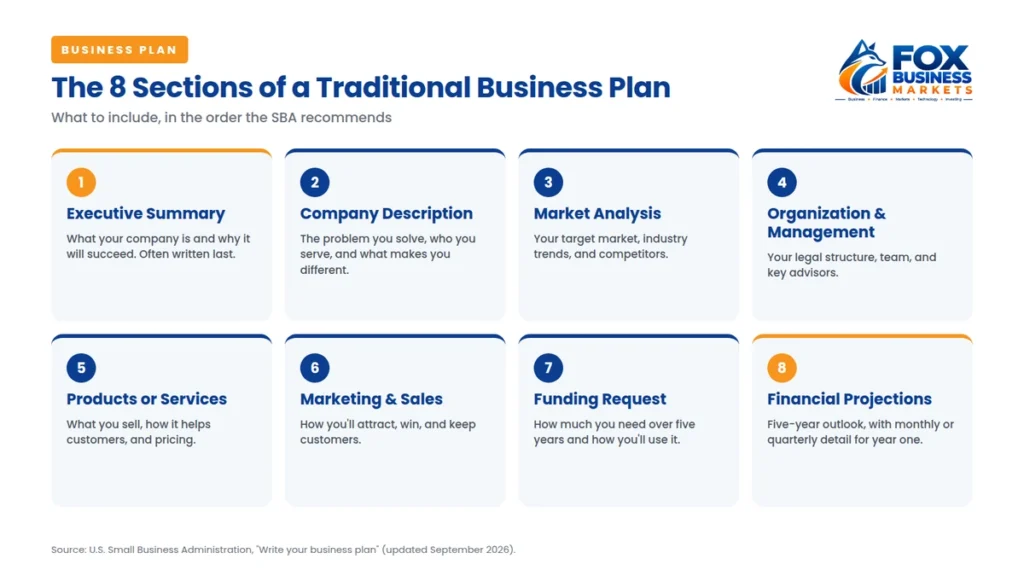
The SBA’s traditional plan has eight sections: executive summary, company description, market analysis, organization and management, service or product line, marketing and sales, funding request, and financial projections.
Can I write a business plan myself?
Yes. Most small business owners write their own plans. Free templates from SCORE and the SBA’s online guide make it easier, and SCORE mentors can review your draft for free.
How far ahead should financial projections go?
The SBA recommends projections for the next five years, with quarterly or even monthly detail for the first year.
Do I need a business plan for an SBA loan?
The SBA says most lenders expect a business plan when you apply for startup funding. Your lender will tell you exactly which documents you need for your loan.
How often should I update my business plan?
Review it at least once a year, and update it whenever you seek funding, launch a new product, or see a major change in your market.
Final Takeaway
Knowing how to write a business plan gives you a clearer path and a better chance of success. Start with a lean, one-page plan to test your idea, then expand it into a traditional plan when you need funding. Keep your numbers realistic, explain what makes your business different, and update the plan as you grow.