1. How to Use the Simple Interest Calculator
The Simple Interest Calculator evaluates linear financing costs and fixed investment yields across customized durations without the mathematical complexity of compounding cycles. Follow these operating steps:
- Select Your Analysis Mode & Currency: Choose between the Borrowing / Loan Cost tab (to evaluate liability obligations) and the Fixed Return / Yield tab (for static asset returns). Pick your currency (USD, EUR, GBP, CAD, or AUD) via the top selector.
- Enter Base Principal: Input the starting amount financed, borrowed, or deposited into the principal input field.
- Specify Fixed Annual Interest Rate (%): Enter the stated nominal simple interest rate per annum.
- Select Duration & Units: Define the term duration using years, months, or exact days. The calculator automatically converts time intervals into standard annualized metrics ($t$).
- Set Payment Schedule Basis: Designate your amortization frequency (Monthly, Quarterly, or Annual Bullet) to view estimated periodic installment obligations in real time.
2. How It Works & Core Mathematical Formulas
Unlike compounding models where accrued yield is reinvested, simple interest accrues in a strictly linear trajectory proportional to original principal capital.
Primary Simple Interest Equation
Total interest generated or owed over time ($I$) is determined using the classic financial equation:
Where:
• I = Total Simple Interest Accrued
• P = Base Principal balance
• r = Nominal annual interest rate (decimal form: 6.5% = 0.065)
• t = Time horizon in years (Days ÷ 365, Months ÷ 12, or Years)
Total Repayment & Terminal Value
The total obligation or gross terminal proceeds ($A$) combines the starting principal with accumulated interest charges:
Daily Interest Accrual Rate
Commercial lenders and bridge loan providers utilize daily statutory interest conventions to establish per diem carrying charges:
3. Fully Worked Numerical Example
Commercial Equipment Financing Analysis
A business secures an uncompounded equipment credit facility under the following terms:
- Principal Loan Amount ($P$): $15,000
- Nominal Simple Interest Rate ($r$): 6.50% (0.065)
- Loan Horizon ($t$): 3 Years
- Amortization Schedule: Monthly Installments (36 periods)
Step 1: Calculate Total Simple Interest Charge ($I$)
I = $15,000 × 0.065 × 3
I = $15,000 × 0.195 = $2,925.00
Step 2: Determine Gross Repayment Balance ($A$)
A = $15,000 + $2,925 = $17,925.00
Step 3: Calculate Daily Accrual and Periodic Payment
Daily Accrual = ($15,000 × 0.065) / 365 = $2.671 per day
Total Installments = 3 years × 12 months = 36 payments
Monthly Payment = $17,925 / 36 = $497.92 (≈ $498 / month)
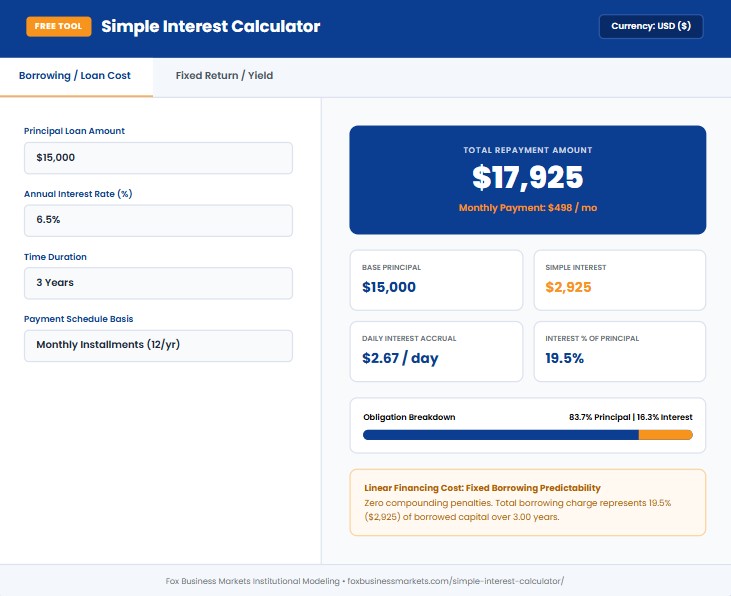
Operational Summary: Simple interest financing keeps borrowing costs entirely static at $2,925 (19.5% of principal), ensuring complete predictability over cash flows across the entire 36-month timeline.
4. Calculator Interface & Cost Breakdown
5. Industry Simple Interest Benchmarks by Debt Class
While long-term consumer mortgages utilize compounding amortization, simple interest structures are standard in bridge lending, automobile finance, and short-term commercial facilities:
| Financing Structure | Typical Duration Term | Prevailing Simple Rate Range | Payment Frequency | Key Commercial Application |
|---|---|---|---|---|
| Automobile Retail Installments | 36 – 72 Months | 5.00% – 9.50% | Monthly | Consumer & fleet vehicle financing where interest calculates per diem. |
| Commercial Promissory Notes | 6 – 24 Months | 7.50% – 12.00% | Quarterly / Bullet | Short-term working capital bridges between enterprise funding rounds. |
| Invoice Factoring & Receivables | 30 – 90 Days | 1.50% – 3.00% / month | Upon Collection | Accelerating liquidity against outstanding customer corporate invoices. |
| Personal Installment Loans | 12 – 60 Months | 8.00% – 15.00% | Monthly | Fixed-term debt consolidation with transparent uncompounded schedules. |
| Intercompany Corporate Loans | 1 – 5 Years | Applicable Federal Rate (AFR) | Annual / Semi-Annual | Internal parent-to-subsidiary treasury transfers ensuring IRS tax compliance. |
6. Where to Find Your Numbers
To accurately configure simple interest models, obtain primary data points from official contract covenants and financial filings:
- Principal Financed ($P$): Extract net disbursed proceeds directly from credit agreements or vehicle purchase contracts. To model leverage safety margins, review our Debt-to-Equity Calculator.
- Stated Simple Interest Rate ($r$): Verify the contractual rate on the promissory note face page. If the contract involves compounding features, compare effective yield using the Compound Interest Calculator.
- Loan Term Duration ($t$): Check maturity dates within loan covenants. For short-term corporate bridges, confirm whether the contract employs a 360-day commercial year or a 365-day statutory standard.
- Debt Repayment Capacity: Confirm your operating cash flows can service periodic monthly burdens using the Business Loan Calculator.
7. What This Calculator Can and Cannot Tell You
What It Can Tell You
- The precise linear dollar cost of credit without exponential compounding escalation.
- Daily per diem accrual rates essential for assessing early payoff interest deductions.
- The exact nominal ratio of interest expense compared to base principal borrowed.
- Standardized periodic payment obligations across monthly, quarterly, and annual intervals.
What It Cannot Tell You
- Origination & Closing Fees: Upfront lender points and closing charges are excluded; use an APR model for true total borrowing costs.
- Early Payoff Amortization Curvature: In real-world installment debt, paying principal early reduces ongoing simple interest calculations daily.
- Late Penalty Fees: Default fees or delinquent interest escalations are not incorporated.
- Tax Deductibility: Business interest tax exemptions depend on jurisdictional net interest expense deduction caps.
8. Related Business & Financial Calculators
Expand your financial modeling toolkit across other specialized Fox Business Markets analysis calculators:
Business Loan Calculator
Model fully amortizing term loans with complete principal and interest payback schedules.
Working Capital Calculator
Measure liquidity cushions and short-term debt servicing capacity against current assets.
Debt-to-Equity Calculator
Evaluate corporate financial leverage ratios and long-term solvency posture.
Compound Interest Calculator
Compare linear simple interest growth against exponential reinvestment trajectories.
9. Frequently Asked Questions (FAQ)
When is simple interest typically used instead of compound interest?
Simple interest is standard in short-term financing where loan balances do not compound unpaid interest into capital. Common examples include automobile financing, fixed-term personal installment notes, short-term vendor credit, invoice factoring, and private promissory contracts between operating companies.
Does early repayment save money on a simple interest loan?
Yes. Because simple interest is computed based on elapsed time ($t$) and outstanding balance ($P$), paying down principal ahead of schedule shortens the time factor, immediately reducing total interest paid over the life of the loan.
What is the difference between ordinary and exact simple interest?
Exact simple interest uses a 365-day year convention ($t = \text{Days} / 365$). Ordinary simple interest (frequently termed the Banker's Rule) uses a 360-day year ($t = \text{Days} / 360$), which slightly inflates annual interest yields for lenders.
Can simple interest be applied to investment portfolios?
Yes. If an investor withdraws cash dividends or coupon distributions immediately rather than reinvesting them back into the asset base, the portfolio produces linear simple yields based strictly on the original capital base.
How does simple interest differ from APR?
Simple interest reflects only the base contractual borrowing percentage applied to principal. The Annual Percentage Rate (APR) incorporates base interest plus all mandatory closing points, broker fees, and administrative charges, showing the true comprehensive cost of credit.
10. The Bottom Line & Authoritative References
Simple interest represents the most direct, transparent borrowing structure in commercial finance. By eliminating exponential recapitalization, it guarantees that borrowing costs or asset returns correlate directly with time and principal. Corporate operators and private borrowers who master simple interest fundamentals can optimize credit agreements, negotiate favorable loan terms, and avoid costly compounding debt spirals.
Authoritative References & Academic Reading:
- Consumer Financial Protection Bureau (CFPB): Guidance on simple interest vs. precomputed interest in consumer lending and auto financing structures.
- Federal Reserve Board (Regulation Z): Truth in Lending disclosure requirements for simple interest credit calculations and amortization statements.
- Internal Revenue Service (IRS Topic 403): Guidelines on interest expense deductibility and statutory rules on Applicable Federal Rates (AFR) for non-compounding promissory notes.
- Brigham, Eugene F., & Ehrhardt, Michael C. (Financial Management: Theory & Practice): Foundational corporate finance literature on linear interest valuation, credit structuring, and cost of capital.