Quick answer: Payment processing is the system that moves money from a customer’s card, bank account, or digital wallet to a business’s bank account. A processor, card networks, and banks approve each payment in seconds and settle the funds, usually within one to two business days. Card payments typically cost businesses about 1.5% to 3.5% per sale.
Americans made 236.6 billion noncash payments in 2024, according to the Federal Reserve’s 2025 Payments Study, and cards accounted for more than three-quarters of them. Each of those card swipes, taps, and online checkouts passed through a payment processor before the money reached a business’s bank account.
That convenience isn’t free. U.S. merchants paid $198.25 billion in card processing fees in 2025, about 1.6% of card purchase volume, according to the Nilson Report. For a small business with thin margins, the difference between a good and a bad processing setup can be thousands of dollars a year.
This guide explains how payment processing works step by step, who handles your money along the way, which payment methods to accept, what processing costs, what the new Visa and Mastercard settlement could change, and how to choose a processor that fits your business.
What Is Payment Processing?
Payment processing is the series of steps that verifies a customer’s payment, approves it, and moves the funds into the seller’s account. It covers card payments in a store or online, bank transfers, digital wallets such as Apple Pay and Google Pay, and newer instant payment networks.
For most businesses, payment processing means accepting credit and debit cards. A payment processor handles the technical and financial work behind each card sale, and charges a fee for every transaction. Other methods, such as ACH transfers, follow different routes and cost structures, which we cover below.
How Does Card Payment Processing Work?
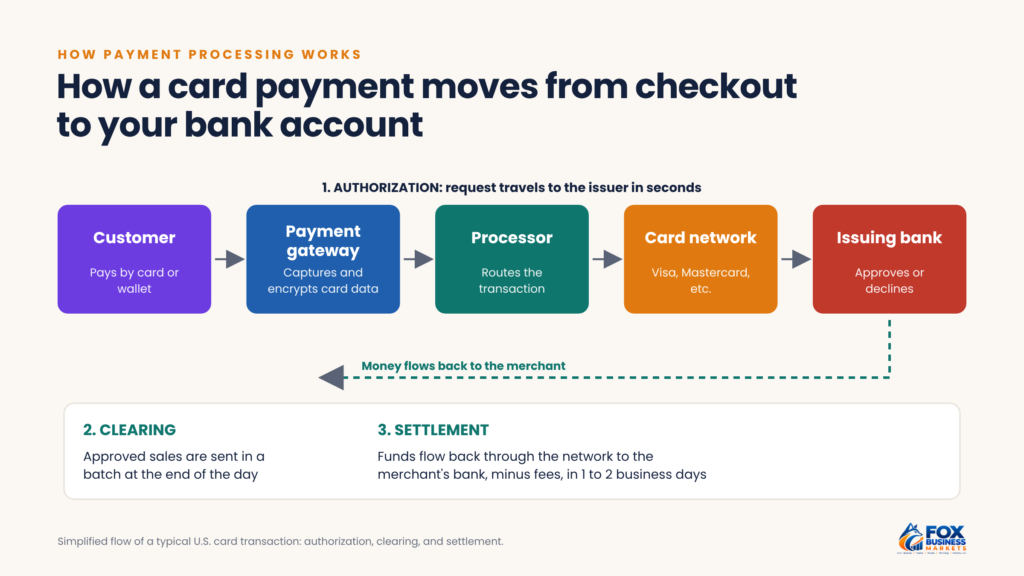
A card payment looks instant at checkout, but several companies are involved behind the scenes:
Player | Role |
| Customer (cardholder) | Pays with a credit card, debit card, or digital wallet |
| Merchant | The business accepting the payment |
| Payment gateway | Securely captures card details online or at the terminal and sends them for approval |
| Payment processor | Routes the transaction between the merchant, card networks, and banks |
| Acquiring bank (acquirer) | The merchant’s bank for card payments; deposits the funds |
| Card network | Visa, Mastercard, American Express, or Discover; sets rules and interchange rates |
| Issuing bank (issuer) | The customer’s bank; approves or declines the charge |
Every card payment moves through three stages:
- Authorization: the customer pays, and the gateway sends the card details through the processor and card network to the issuing bank. The issuer checks for available funds or credit and possible fraud, then approves or declines the charge, usually within seconds.
- Clearing (batching): at the end of the day, the merchant’s approved transactions are sent as a batch for final processing.
- Settlement: the issuing bank sends funds through the card network to the acquiring bank, which deposits them in the merchant’s account, minus fees. This usually takes one to two business days, though some processors offer faster payouts for an extra fee.
What’s the Difference Between a Processor, a Gateway, and a Merchant Account?
These terms are often used interchangeably, but they describe different pieces of the setup:
Component | What it does | Do you always need it? |
| Merchant account | A special bank account that holds card sales before they’re moved to your business bank account | No; payment facilitators group many businesses under one master account |
| Payment gateway | The technology that captures and encrypts card data, mainly for online sales | Yes for online sales; often built in |
| Payment processor | The company that moves transaction data and funds between parties | Yes |
| Payment facilitator | A provider such as Square, Stripe, or PayPal that bundles all three and lets you sign up in minutes | Optional alternative to a traditional merchant account |
Payment facilitators are the easiest option for new and small businesses: quick approval, simple flat-rate pricing, and no separate merchant account. Traditional merchant accounts take longer to set up and require underwriting, but often offer lower rates and fewer sudden fund holds for businesses with higher sales volume.
How Do In-Person, Online, and Mobile Payments Differ?
Card networks sort every sale into one of two groups. Card-present transactions happen when the customer’s card or phone is at your terminal. Card-not-present transactions happen online, by phone, or through a payment link. Card-not-present sales usually carry higher interchange rates and more fraud risk, because you can’t check the physical card.
Your setup depends on where you sell:
- Storefronts: a point-of-sale (POS) system with an EMV chip and contactless reader.
- Online stores: a gateway built into your e-commerce platform or checkout page.
- Mobile and pop-up sales: a card reader paired with a phone or tablet app.
- Phone orders and invoices: a virtual terminal or emailed payment links.
Many processors cover all four channels under one account, which keeps reporting and payouts in one place.
Which Payment Methods Should Your Business Accept?
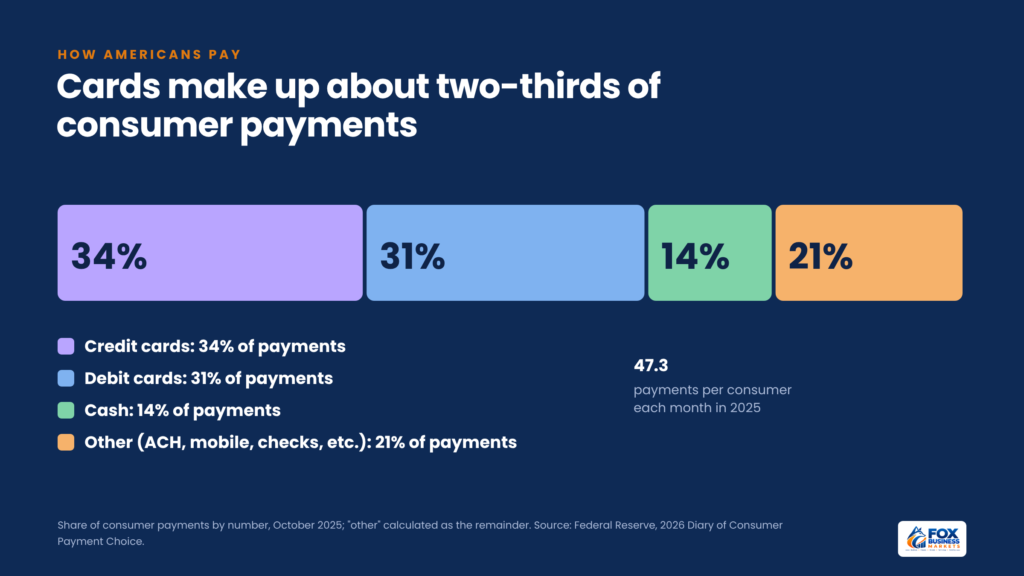
The right mix depends on who your customers are and how they like to pay. Consumers made about 47 payments a month in 2025, and credit cards (about 34%) and debit cards (about 31%) were the most used, followed by cash at about 14%, according to the Federal Reserve’s 2026 Diary of Consumer Payment Choice. Our payment statistics roundup tracks these trends over time.
Method | Typical cost to the business | Speed | Best for |
| Credit cards | About 1.5% to 3.5% per sale | 1 to 2 business days | Retail, restaurants, online stores |
| Debit cards | Often lower than credit | 1 to 2 business days | Everyday consumer purchases |
| ACH bank transfers | Low flat fees or a small percentage | 1 to 3 business days; same day available | Invoices, subscriptions, B2B payments |
| Wire transfers | Flat bank fees, often charged to sender and receiver | Same day | Large or urgent payments |
| Instant payments (RTP, FedNow) | Low per-payment fees | Seconds, 24/7 | Time-sensitive payments where your bank supports it |
| Digital wallets (Apple Pay, Google Pay) | Usually same as the card behind them | Same as cards | Mobile and contactless checkout |
| Buy now, pay later (BNPL) | Often higher than cards | Paid in full, usually within 1 to 3 business days | Higher-priced online purchases |
| Checks | Handling, deposit, and fraud risk | 1 to 5 business days, longer if held | Some B2B customers |
| Cash | Handling, counting, and security costs | Immediate | In-person sales |
ACH is the backbone of bank-to-bank payments in the U.S. The ACH Network handled 35.2 billion payments worth $93 trillion in 2025, according to Nacha, which runs the network. Business-to-business ACH volume grew almost 10%, to about 8.1 billion payments. For the history of how payment systems developed around the world, see our overview of payment methods and payment systems.
Most businesses should accept cards and digital wallets at a minimum. If you send invoices to other businesses, add ACH, which costs far less than cards on large payments. Our guide to ACH payments explains how to set it up.
How Much Does Payment Processing Cost?
Every card transaction carries three layers of cost:
- Interchange: the largest share, paid to the customer’s card-issuing bank. Rates are set by the card networks and depend on the card type, how it’s used (in person or online), and the type of business. Rewards and premium cards carry higher rates.
- Network (assessment) fees: smaller fees paid to Visa, Mastercard, and other networks.
- Processor markup: what your processor charges for its service. This markup, along with any add-on fees, is the part you can negotiate.
Processors bundle these costs into a few pricing models (flat-rate, interchange-plus, tiered, and subscription), and the right one depends on your sales volume and average sale size.
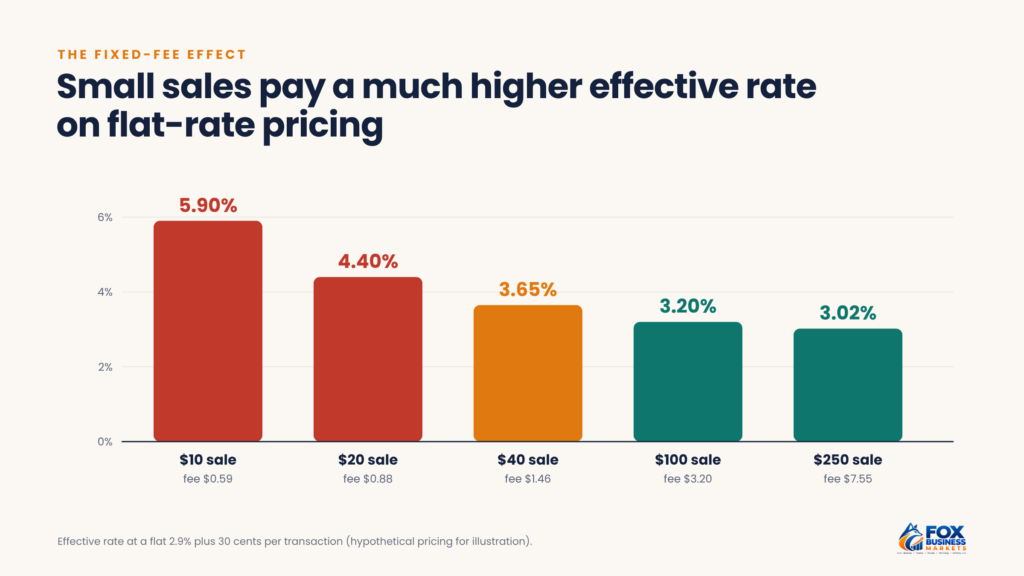
Example: a shop with $50,000 in monthly card sales and an average sale of $40 processes 1,250 transactions a month. At a flat rate of 2.9% plus 30 cents, it pays $1,450 plus $375, or $1,825 a month, an effective rate of 3.65%. Small average tickets make the fixed per-transaction fee add up quickly. Our guide to credit card processing fees compares each pricing model, explains interchange in detail, and shows how to calculate your own effective rate.
Watch for other charges, too: monthly or annual account fees, PCI compliance fees, chargeback fees, early termination fees, and equipment leases that can cost more than buying a terminal outright.
What Does the Visa and Mastercard Settlement Mean for Merchants?
On June 9, 2026, a federal judge gave preliminary approval to a settlement between Visa, Mastercard, and U.S. merchants over card fees, valued at roughly $38 billion in merchant savings. A final approval hearing is set for November 16, 2026, according to Payments Dive. If it receives final approval, key terms include:
- Lower credit card interchange for several years, including a cap on standard consumer credit cards.
- More choice over which cards to accept, including the right to decline some premium and commercial cards, a break from the long-standing “honor all cards” rule.
- More room to surcharge or offer discounts that steer customers toward cheaper payment methods.
Hundreds of merchants and trade groups have objected, and some have said they’ll appeal if the deal is approved, so changes may take time to reach your statement.
Any savings depend on your processor passing lower interchange through to you. Businesses on interchange-plus pricing are more likely to see the benefit directly than those on flat-rate plans. See our credit card processing fees guide for the rate details.
Is It a Myth That You Can’t Negotiate Processing Fees?
Yes. Many business owners assume card fees are fixed, but only part of each fee is. Interchange and network fees are set by the card networks and are the same no matter which processor you use. The processor’s markup and add-on fees, however, are often negotiable, especially once you have a steady sales history.
To lower your costs:
- Get at least three quotes based on your actual monthly volume and average sale size, and compare the processor markup, not just the headline rate.
- Ask to remove or reduce add-on fees, such as monthly minimums, PCI fees, and statement fees.
- Avoid long contracts with early termination fees, or negotiate the fee away before you sign.
- Use your history. After six to 12 months of steady processing, ask your current provider to lower its markup.
How Do You Choose a Payment Processor?
Compare processors on more than price. Use this checklist:
- Total cost at your volume: ask for an estimate based on your actual monthly sales, average transaction size, and card mix.
- Pricing model: prefer interchange-plus or a transparent flat rate over tiered pricing.
- Payment methods supported: cards, digital wallets, ACH, and any methods your customers expect.
- Sales channels: in-person, online, invoicing, recurring billing, or all of them.
- Payout speed: standard deposit timing and the cost of faster payouts.
- Integrations: compatibility with your point-of-sale system, e-commerce platform, and accounting software.
- Contract terms: length, cancellation fees, and equipment ownership.
- Security and support: fraud tools, chargeback help, and reachable customer service.
- Account stability: payment facilitators can freeze or hold funds for unusual activity, so read their policies on reserves and holds.
How Do You Set Up Payment Processing?
Most businesses can start accepting payments within a day with a payment facilitator, or within one to two weeks with a traditional merchant account. The steps are similar either way:
- Decide where you’ll sell: in person, online, by invoice, or a mix.
- Gather your documents: your EIN or Social Security number, business bank account details, ID, and a description of what you sell.
- Apply and pass underwriting: the provider reviews your business type, expected volume, and credit to set your limits and any reserve.
- Set up hardware and software: connect your reader, POS system, or online checkout, and link your accounting software.
- Run a test transaction and refund it, then confirm the deposit reaches your bank account.
- Turn on fraud tools and notifications before you go live, so you see disputes and payout problems early.
Keep your application details accurate. A mismatch in business type or expected sales is a common reason for later fund holds.
How Do You Keep Payments Secure?
Any business that accepts cards must follow the Payment Card Industry Data Security Standard (PCI DSS), a set of rules for protecting cardholder data. Version 4.0.1 is the current standard. Most small businesses confirm compliance by completing an annual self-assessment questionnaire through their processor.
Practical steps to reduce fraud and disputes:
- Never store full card numbers. Use your processor’s tokenization, which replaces card data with a secure token.
- Use EMV chip readers and contactless terminals for in-person sales.
- Turn on fraud tools such as address verification (AVS) and card security code (CVV) checks for online orders.
- Write clear refund policies and use a recognizable business name on customer card statements to reduce chargebacks.
- Respond to chargebacks quickly with receipts, delivery confirmation, and customer communications.
How Do Payments Affect Your Cash Flow?
Payment timing shapes how much cash you have on hand. Cards and ACH settle within days, but invoices on net 30 or net 60 terms can leave you waiting a month or more. Processing fees, refunds, and chargebacks also reduce what lands in your account.
To keep cash flowing:
- Offer several ways to pay on every invoice, including ACH and cards, so customers can pay immediately.
- Track your effective processing rate monthly as a share of total sales.
- Match payout timing to your bills, such as payroll and rent.
- Send invoices promptly with clear due dates; our guide on how to invoice covers payment terms and follow-up.
Our guides to cash flow management and small business finance show how payment timing fits into your broader financial plan.
What Payment Terms Should You Know?
Term | Meaning |
| Effective rate | Total fees divided by total card sales |
| Chargeback | A disputed charge reversed by the customer’s bank |
| Rolling reserve | A share of sales a processor holds back to cover future disputes |
| Tokenization | Replacing card numbers with a secure stand-in |
| Batch | A day’s approved sales submitted together for settlement |
| Payout | The deposit of settled funds into your bank account |
Frequently Asked Questions
Can you charge customers a credit card surcharge?
In most states, yes, but only for credit cards, not debit or prepaid cards. Card network rules cap surcharges (Visa limits them to the lesser of 3% or your processing cost) and require advance notice to your processor and clear disclosure to customers at the store entrance, at checkout, and on receipts. Connecticut, Maine, and Massachusetts ban surcharges, and states such as Colorado cap them, so check your state’s rules before adding one.
Do you need a business bank account to accept card payments?
Most processors require a bank account to deposit your sales, and many payment facilitators let sole proprietors use a personal account. A separate business account still makes bookkeeping and taxes much easier; our guide to choosing a business debit card covers what to look for. Open one before you start accepting payments so every sale lands in the same place.
Are payment processing fees tax-deductible?
Yes. Card processing fees, gateway fees, and related charges are generally deductible as ordinary and necessary business expenses. Keep your monthly processor statements, because they show the total fees you paid. Ask your accountant to record sales at the gross amount and the fees as a separate expense, so your books match the gross figures on any Form 1099-K you receive.
What is a high-risk merchant account?
A high-risk merchant account is for businesses that processors see as more likely to have chargebacks or fraud, such as travel, subscription, CBD, or online gaming businesses. These accounts often carry higher rates, rolling reserves, and longer contracts. If your business falls into a high-risk category, disclose it upfront to avoid having your account frozen later.
Audit Your Payment Costs This Month
Pull your last three processor statements, add up every fee, and divide by your total card sales to find your effective rate. Compare it with at least two quotes on interchange-plus pricing, and ask your current processor to match the best offer. Then review which payment methods you accept, add ACH for larger invoices, and turn on the fraud tools you’re already paying for. For a closer look at card pricing, start with our guide to credit card processing fees, and see our credit card statistics for how consumers use cards.
This article is for general information only and isn’t financial, tax, legal, or investment advice. Consider your own situation or talk to a qualified professional before making decisions.

